


Bad credit or no credit history does not automatically stop you from getting a title loan from Swift Title Loans.
You may still qualify if your vehicle has enough value and you have steady income we can verify, such as income from employment, self-employment, or eligible benefits. Been through a bankruptcy? A past bankruptcy does not automatically disqualify you either.
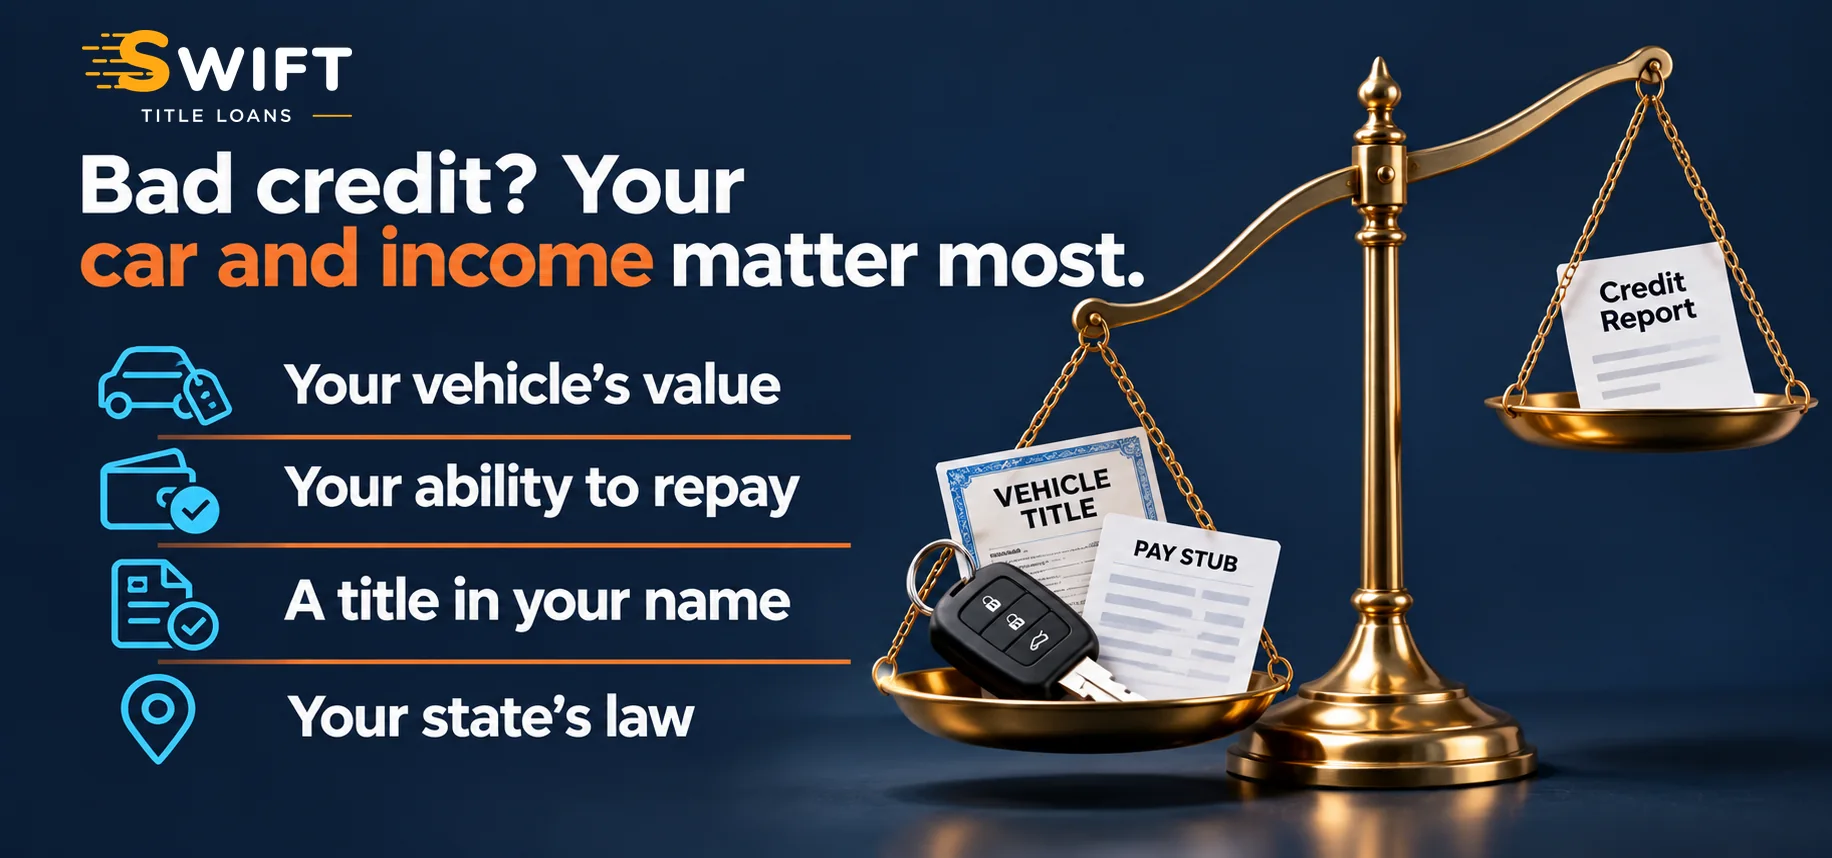
A title loan is a secured loan that uses your vehicle as collateral. When reviewing your application, we look mainly at your vehicle’s value and your ability to repay, rather than your credit score alone. The title must be in your name and usually lien-free or nearly paid off.
You can check if you pre-qualify online by providing basic information about yourself, your income, and your vehicle. Checking if you pre-qualify does not affect your FICO® Score.
Keep in mind that title loans can cost much more than loans from a bank or credit union. If you cannot repay the loan, your vehicle may be repossessed under your loan agreement and state law. Before signing, review the APR, payment amount, and total cost to make sure the loan fits your budget.
Quick Answers
- Can you get a title loan with bad credit? You may, if your vehicle has enough value, you have income we can verify, and you meet your state’s requirements.
- Will checking if you pre-qualify hurt your score? No. Checking if you pre-qualify does not affect your FICO® Score, even if your credit is already low.
- Are there lower-cost options with bad credit? Possibly. A credit union, payment plan, or another lower-cost option may still be available even with bad credit.
- Can a lender guarantee approval with bad credit? No. Every application must be reviewed, so be careful with companies that promise guaranteed approval regardless of your credit.
Why Your Credit Score Matters Less for Approval
Your credit score isn’t the main thing we look at. We focus mainly on two things:
- Your vehicle’s value. This helps determine how much you may qualify for.
- Your ability to repay. You need income we can verify and enough room in your budget to make the payments.
We also look at:
- Your title. This is where we place our lien. It should be in your name and usually lien-free or nearly paid off.
- Your state’s law. Each state regulates title loans differently, so loan amounts, costs, and requirements depend on where you live.
Do You Need a Job to Get a Title Loan?
You don’t need a traditional job, but you do need income you can show, because that’s how we know you can make the payments. It can come from:
- Work: a job or self-employment
- Benefits: Social Security, disability, workers’ compensation, or other benefits
- Other income: retirement, alimony, or other income you can prove
Got income but not much paperwork? Read whether title loans without proof of income are possible.
How Much Could You Borrow Even With Bad Credit?
How much you can borrow depends mainly on your state’s law, your vehicle’s value, and your income. Bad credit generally has less impact on the loan amount because your vehicle secures the loan.
We typically lend about 25% to 50% of your vehicle’s value. For example, a $10,000 vehicle may support a loan of about $2,500 to $5,000, depending on your ability to repay and state limits. The smallest title loan is usually around $100.
Examples from our lending experience and state law:
- California: Most funded title loans range from about $2,800 to $6,000.
- Florida: Most funded title loans range from about $800 to $3,100.
- Texas: Funded title loans since mid-2025 have often ranged from about $600 to $2,200.
- Virginia: State law limits title loans to $2,500.
- Tennessee: State law limits title loans to $2,500 per vehicle title.
For a rough estimate, use our title loan calculator or read more about how much you may be able to borrow.
Do We Check Your Credit?
Submitting a loan request to Swift Title Loans does not affect your FICO® Score. We may check your background through a non-traditional consumer reporting agency. That check could show up on your record with the agency in question, but it has no impact on your FICO® Score.
You may see ads promising title loans with “no credit check.” A title loan may rely less on your credit score than a bank loan, but approval is never automatic. We still review your vehicle, your income, and other information before we decide.
What Can Still Stop a Title Loan Approval?
Even if your credit score is not the issue, other things can still affect approval:
- The title is not in your name. The name on the title should match your ID. If the title is in someone else’s name, it may need to be transferred first, or the titled owner may need to be involved.
- You still owe too much on the car. A title loan may still be possible with a small remaining balance, but a larger lien can make approval harder.
- You are asking for more than the car supports. The amount has to fit your vehicle’s value, your ability to repay, and your state’s limits.
- We cannot verify the vehicle. Photos usually let us confirm the car’s condition and value, but an in-person inspection may still be needed in some cases.
- Required documents are missing. You will need a government-issued photo ID and may also need proof of address, income, and auto insurance, depending on the loan and your state. See our title loan requirements.
Some issues can be fixed, such as paying down a remaining balance or correcting the title, so ask us what may need to change before applying again.
What Could a Title Loan Cost You?
Your credit score does not change your state’s legal rate limits. If your state sets a cap, the same cap applies whether your credit is good or bad.
California: $2,500 to $9,999
State law allows up to 36% a year plus the Federal Funds Rate, about 39.63% in August 2026. At that limit over 12 months, a loan would cost about:
- $3,000 loan: $307 a month, $682 total interest
- $5,000 loan: $511 a month, $1,137 total interest
California: $10,000 or more
California sets no state rate cap on these loans.
Other states
Rates, fees, and limits vary. Some states set specific caps, while others use different fee structures.
Industry comparison
A CFPB study of single-payment title loans found APRs of around 300%. This is an industry figure, not a Swift Title Loans rate.
These are legal limits and industry examples, not a quote for your loan. Your exact cost depends on your vehicle, loan amount, term, and state law.
Before you sign, Swift Title Loans shows you the APR, payment amount, and total cost of the loan.
What Is at Risk if You Fall Behind?
Before you borrow, make sure the payment fits your budget. If it only works when nothing unexpected happens, the loan may be too expensive for you.
If you fall behind, your loan can go into default and your vehicle may be repossessed under your state’s law. In some states, you could still owe money if the sale of your vehicle doesn’t cover the loan.
If you think you may miss a payment, contact us before the due date. We may be able to explain your options before the situation gets worse.
As long as you stay current, you keep and drive your vehicle. We remain the lienholder on the title until the loan is paid off.
What Other Options Can You Try With Bad Credit?
Even with bad credit, you may still have lower-cost options than a title loan. Before using your vehicle as collateral, consider:
- A credit union loan. Some federal credit unions offer small payday alternative loans that cost much less than a car title loan.
- A payment plan. Ask the company or person you owe whether you can split the amount into smaller payments.
- Family or friends. Borrowing from someone you trust may cost less, as long as you agree on clear repayment terms.
A title loan may be an option when these choices are not available and you need money for an urgent expense, such as a car repair, medical bill, or housing payment. Because title loans can be expensive and put your vehicle at risk, they are generally better suited to short-term needs than everyday expenses.
Frequently Asked Questions
Can Any Lender Guarantee Approval?
No. Every application has to be reviewed first, so not everyone who applies will qualify.
Be careful with companies that promise guaranteed approval, especially if they say your financial situation does not matter.
Can You Get a Title Loan After Bankruptcy?
Yes, you may still be able to qualify after a bankruptcy, because your credit history alone doesn’t decide it.
Can You Get a Motorcycle or RV Title Loan With Bad Credit?
Possibly. If we offer title loans on your type of vehicle, bad credit does not automatically disqualify you. The same things still matter.
How Can You Improve Your Credit Before Borrowing?
Paying reported bills on time and keeping credit card balances low can help improve your credit over time.
If you have bad credit and do not need money immediately, improving your credit may help you qualify for lower-cost borrowing options later. A title loan should not be used as a way to repair your credit.
Can You Get a Title Loan With Bad Credit in Your State?
You may, if Swift Title Loans offers title loans in your state and you meet the requirements.
Start with your state page:
You can also complete our online application in about 7 minutes to see if you pre-qualify and receive a free estimate. Pre-qualification is not final approval. If you continue, we will review your documents and vehicle before showing you the final loan terms and cost.
